

Crude flat markets ended the week with moderate loss after falling over 2 pct on Friday. Both the benchmark futures opened the week with downside pressure on U.S-Iran diplomatic optimism & traders took some short covering, taking risk off table. The rally was pulled up on diplomatic roadblocks along with a physical barrel shortage.
Timespreads moved up this week. Brent prompt futures spreads rose and DFLs (Dated to Frontline) doubled to more than $10/bbl. Prompt market price structure curves moved into deep backwardation due to mounting scarcity of physical barrels despite improving inflow through SoH. Import appetite is rising despite higher oil prices.
Inventories data painted a mixed picture across major hubs. Crude stocks build up while products are drawn across. ARA reported a moderate build in crude while sharp decline was reported from SG markets.
Refined products markets dipped this week from last week’s heights. US diesel crack spreads fell back by $20/bbl and gasoline shedding more than $10/bbl driven by the US exploring the options to prohibit or at least limit diesel exports after domestic prices climbed to a near record in real terms and stocks remain at the lowest for more than four decades despite record refinery production.
Speculators data reported moderate selling across crude F&O over the past week through Tuesday. As per ICE data, Money managers reduced their net length in Brent crude oil futures and options by 64543 to 218114 in the week ending Sep 22nd. Longs left while shorts built up positions.
FUEL OIL MARKETS – SUMMARY
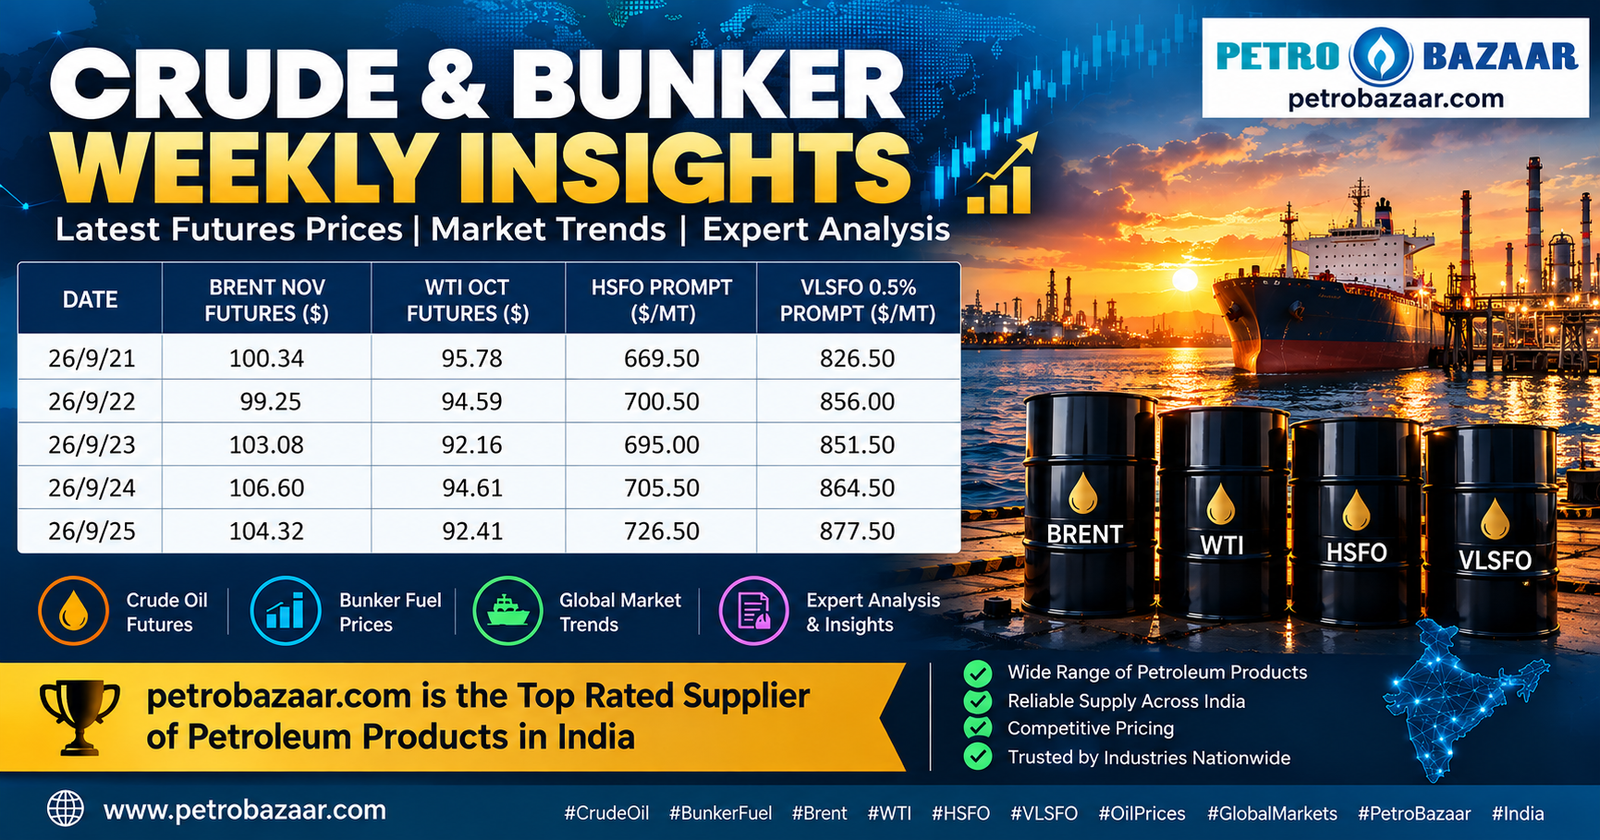
Singapore fuel oil markets remain firm with a moderately bullish sentiment, although rising inventories provide a counter-signal. VLSFO 0.5% prompt prices have strengthened from $826.50/MT to $877.50/MT, while HSFO increased from $669.50/MT to $726.50/MT over the reported period. The VLSFO–HSFO Hi-5 spread has narrowed from $157/MT to $151/MT, indicating relatively stronger HSFO momentum. Singapore residual fuel-oil inventories around 20.3 million barrels, approximately 7% above August levels, are mildly bearish, but continued physical demand, tighter prompt availability and stronger HSFO bunker sales are providing support. Predictive analytics suggest a firm near-term bias for both VLSFO and HSFO, with HSFO showing comparatively stronger momentum, while the key indicators to monitor are Singapore inventory nos, refinery output, prompt physical premiums, crude