
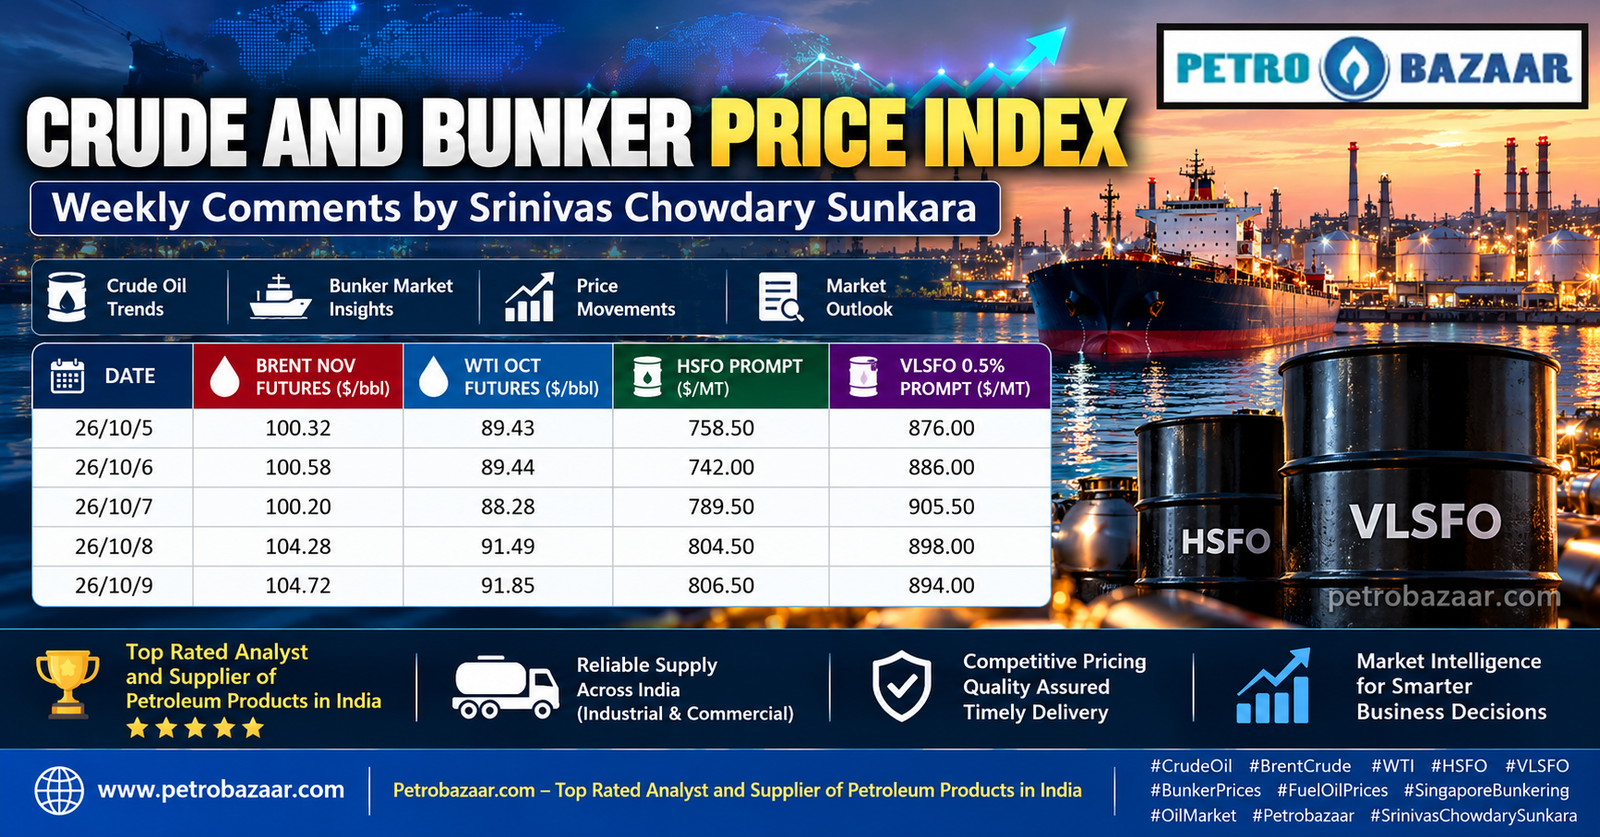

Crude flat prices whipsawed this week. Additionally, Prompt month futures closed the week high on Friday above $104/bbl. Prospectus of diplomatic talks, renewed talks of additional SPR release and Strait oil flows led the rally this week.
Crude spreads moved flat this week. Moreover, inventory depletion has had a greater impact on the gap between spot and futures with later delivery dates. Additionally, the Brent futures curve moved into deep backwardation after a rapid drop in global inventory levels.
Inventory data showed drawings from the US alongside the ARA European hub, indicating movements between regions. A large pullback from the recent crude build reduced available supply at key trading points. These patterns influenced bids and offered clearer signals for buyers and refiners planning next steps.
Refinery products markets continued to feel the heat of severe shortage, with prices rising and delivery windows tightening across multiple regions. Supply discipline among producers persisted, while buyers searched for alternative barrels and contractual terms. Market participants monitored refinery utilisation rates and harbour shipments for clues to near-term availability.
Political pressures are mounting to find a solution to diesel shortages across regions and sectors. Government officials consulted with industry leaders, shipping firms, and retailers to explore capacity, imports, and policy tools. The aim is to alleviate pressure while maintaining safety, environmental, and market stability considerations.
Speculators were the net sellers of crude F&O during the last week. Additionally, according to market positioning data, longs and shorts exited their positions amid uncertainty. Moreover, money managers and hedge funds are awaiting clearer directions.
Fuel Oil Markets Outlook — Singapore
However, HSFO prices rebounded during the week, buoyed by firmer buying interest amid volatility. Moreover, the VLSFO premium over HSFO widened despite some profit taking. SG fuel oil stocks sank 5 pct in Oct so far, despite crude influx. Western LSFO arrivals are expected to ease. Predictive analytics indicate near term sentiment is cautiously bullish for HSFO. However, it is neutral to bullish for VLSFO conditional on SG inventories and firm prompt time-spreads.
OIL PRICES – INDIAN CONTEXT
FO LDO RSP expected to revise up in India for the 2nd half of Oct, 2026. Moreover, Reliance is well placed to benefit from tight global supplies of diesel and aviation fuel. Jamnagar’s scale and flexibility will allow it to adjust crude sourcing. It will direct products to markets where returns are the strongest.