
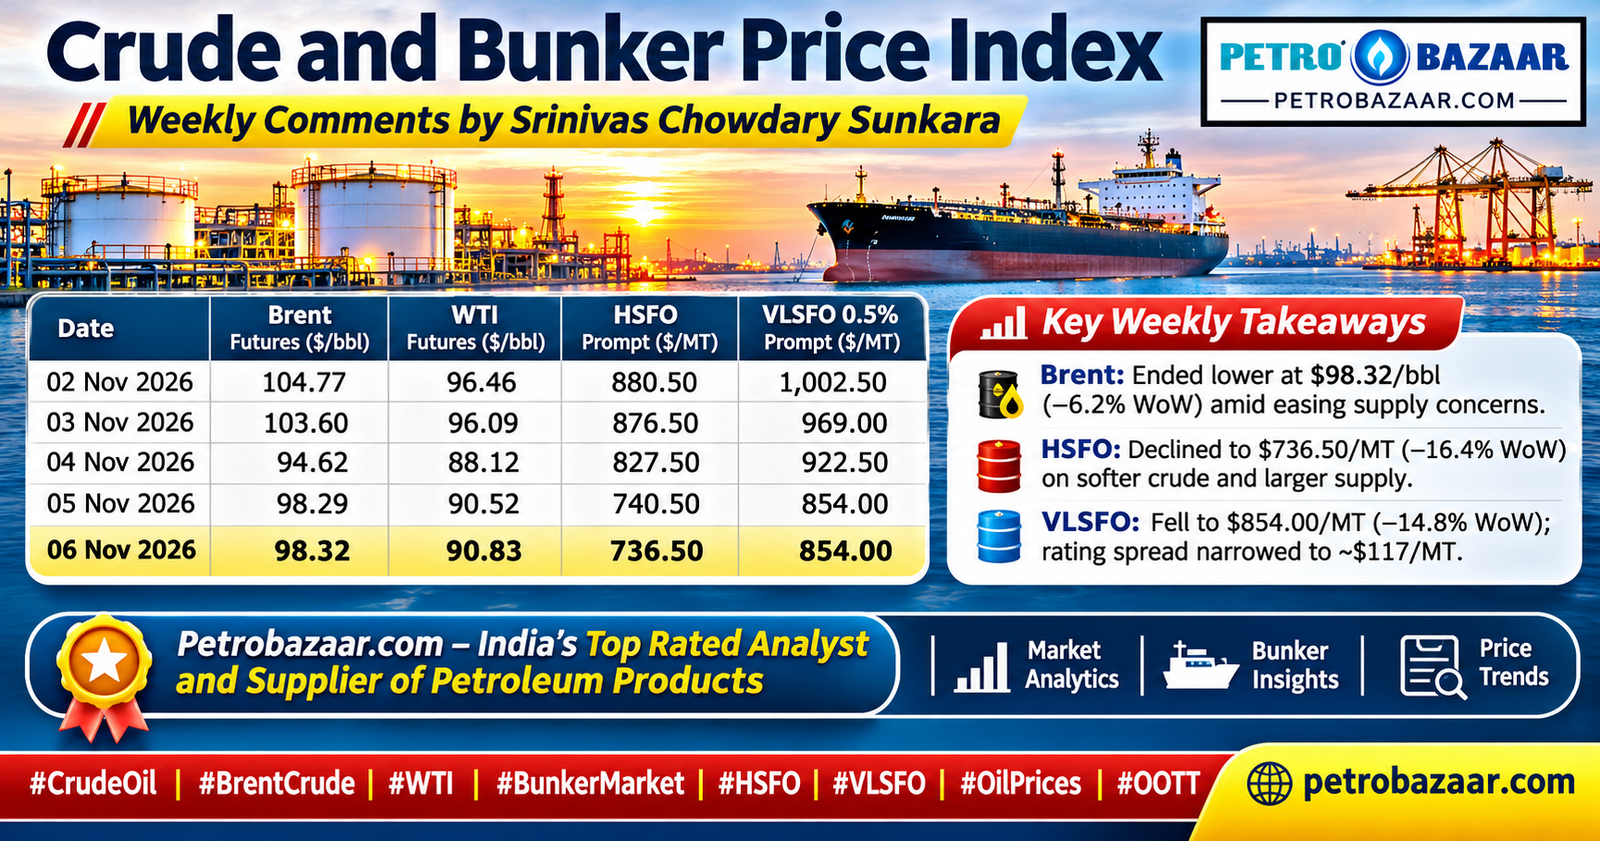

Crude flat prices ripped down this week to close the week just above $90, around 20 pct correction. Pull back from hedges in the absence of expected mid term strikes and massive democrats victory in US midterm elections weighed on. Timespreads traded flat to lower, Brent Jan-Feb price structure curve remained in backwardation, demonstrating premium. Weekly data leaned bullish with large draws reported from the U.S along with seasonal low in SG and a moderate build in ARA Europe. Refined products markets continue to bounce, largely focussed on diesel. Turning to technicals, Speculators data showed that Money managers reduced their net-length in Brent crude F&O by 63487 to 181970 in the week ending Nov 3rd. Longs fell by 47721 while shorts built up by 15766. Net length widened by 75303.
Fuel oil markets on the slippery slope in Asia at SG trading window. Both HSFO and VLSFO logged in around 20 pct correction during the week. SG HSFO declined from $916/Mt on 30th Oct to $732/Mt on 6th Nov while VLSFO fell from $1019.50/Mt to $854/Mt. Both the Forward price structure turned into Contango structure, Indicating bearish sentiment near term. Hi5 spread narrowed sharply during the correction. Keep an eye on cash diff recovery, and regional supply flows. LPG physical market fundamentals are supportive with tightening of supplies while speculative exposure should be treated cautiously. Furnace oil (FO), Light Diesel Oil (LDO) LSHS and MTO prices are very likely to see down side pressure in the next revision in India.